

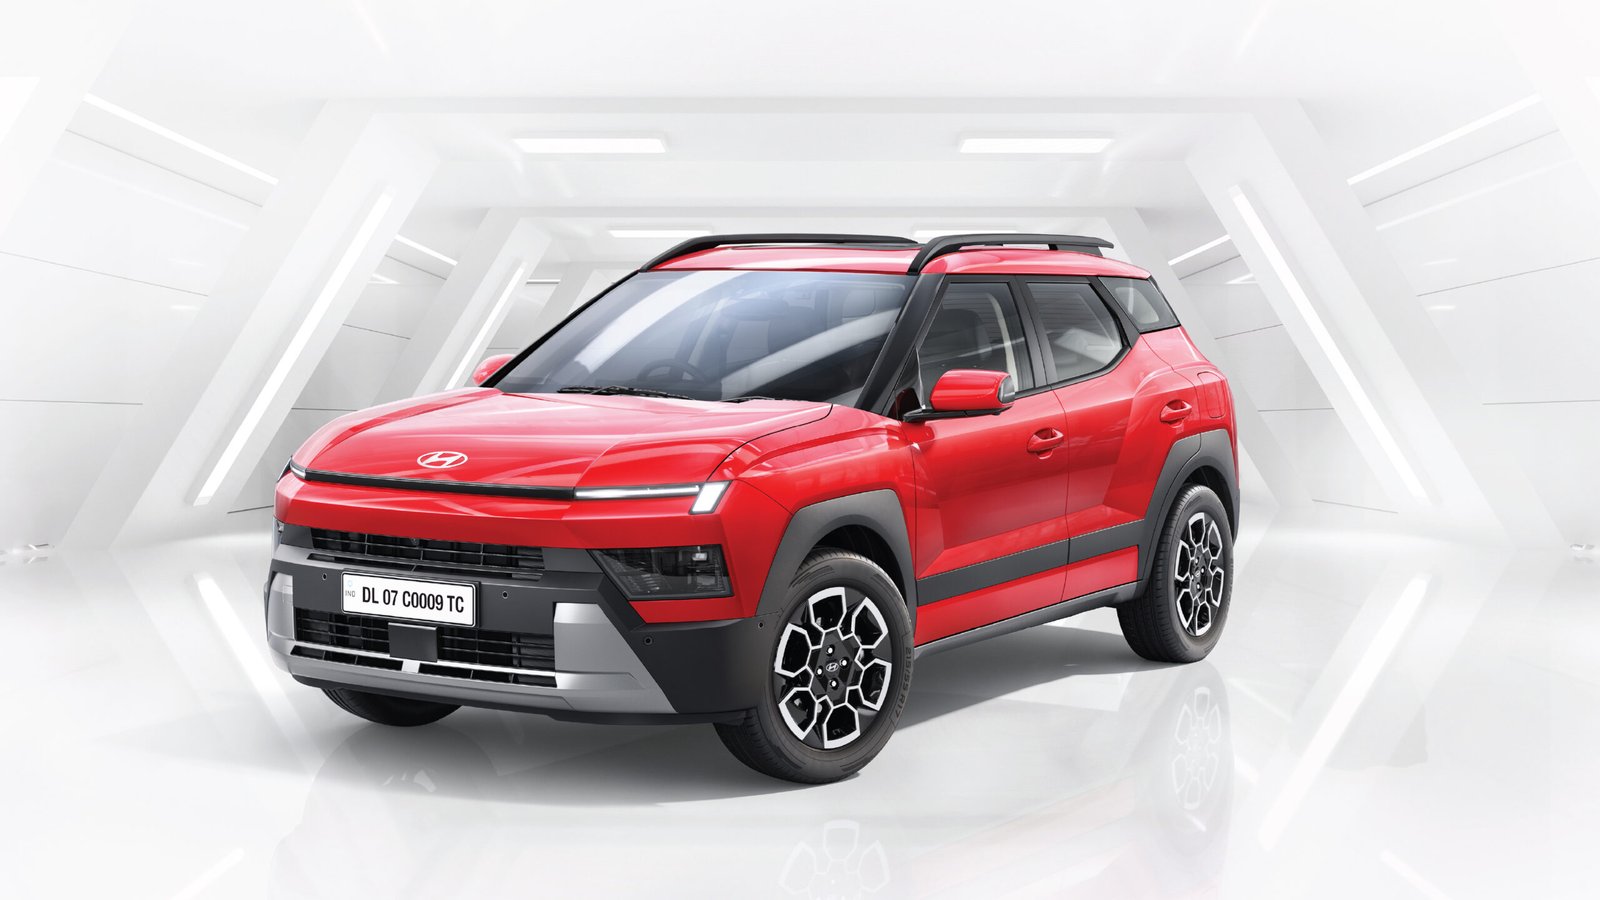
Hyundai Motor India Limited (HMIL) has announced the introduction of a Usage-Based Insurance (UBI) program designed for its connected-car customers across India. Operating through the company’s proprietary Bluelink platform, the initiative allows vehicle owners to potentially receive reductions on the own-damage portion of their insurance renewal premiums by sharing data regarding their driving performance.
Under this program, eligible customers with Bluelink-equipped vehicles whose insurance renewals fall within a 90-day window can monitor their driving behavior directly through the Bluelink application. Driving scores are evaluated using data collected over the preceding three months, focusing on key parameters such as driving dynamics—including rapid acceleration, deceleration, and braking—speed control, and idling times. Customers who attain a score of 70 or above become eligible for potential insurance discounts of up to 15 percent, subject to the specific underwriting criteria of participating insurance partners. Those with lower scores receive driving tips within the application to help improve their performance over time.
The initiative functions through Hyundai India Insurance Broking (HIIB), which acts as an intermediary to facilitate consent-based data transfer between vehicle owners and participating insurance companies. Phase 1 partners for the rollout include Cholamandalam MS General Insurance, Go Digit General Insurance, and ICICI Lombard General Insurance. HMIL states that the UBI program is part of its broader connected mobility strategy, supporting its target to expand its connected-car ecosystem to 2 million vehicles by 2030.
HOWEVER, Usage-Based Insurance (UBI) policy uncovers strategic gaps, and potential consumer friction points.
Device-Free & Seamless Integration: A major friction point in traditional UBI models is the need to install aftermarket telematics hardware or plug-in OBD dongles. Hyundai successfully eliminates this hurdle by leveraging its factory-fitted Bluelink connected-car platform.
Transparency on Criteria: The policy clearly highlights core evaluation parameters— Driving Dynamics (acceleration/deceleration/braking), Speed Control, and Idling Behaviour —alongside a transparent baseline threshold (a score of 70 or above).
Consent-Driven Ecosystem: Utilizing Hyundai India Insurance Broking (HIIB) as an intermediary with explicit opt-in mechanics ensures that data-sharing remains user-consented, addressing modern digital privacy sensitivities. The Data then can be used for future car purchases.
Critical Gaps & Weaknesses in Policy Presentation
Vague Financial Incentives (“Up to 15%”): The headline figure of “up to 15% savings” is heavily watered down by the recurring caveat—*(basis insurers’ underwriting rules)*. Because final discounts depend entirely on individual insurer discretion, consumers face a “bait-and-verify” risk where a high score of 85+ might still yield minimal actual savings.
The “Black Box” Scoring Algorithm: While the metrics (braking, speeding, idling) are listed, the “weighting distribution” is entirely hidden. Drivers do not know whether a sudden brake to avoid a pothole penalizes them more heavily than continuous slight speeding, rendering the score difficult to actively manage.
Exclusionary Ecosystem (Phase 1 Bottlenecks): By restricting initial partnerships to just three insurers (*Cholamandalam MS, Go Digit, and ICICI Lombard*), customers locked into other preferred insurance providers are shut out from the program, forcing them to switch insurers to reap any benefits.
Future Outlook & Strategic Concerns (The “Future”)
The Risk of Penalizing Urban Congestion (Context Blindness): Driving metrics like *idling behaviour* and *rapid deceleration* are heavily skewed by chaotic urban traffic conditions (e.g., bumper-to-bumper traffic in metro cities like Mumbai or Bengaluru). If the algorithm cannot distinguish between aggressive driving and unavoidable city gridlock, urban commuters will be unfairly penalized despite safe driving intents.
Potential for Premium Surcharges: While the current press release focuses strictly on *rewards and savings*, the logical evolution of UBI in global markets eventually introduces **penalties**. Future iterations risk raising baseline premiums for drivers who fall below the score threshold, turning a “bonus” scheme into an intrusive surveillance mechanism.
Data Dependency & Lock-In: As HMIL scales its connected car targets (aiming for 2 million cars by 2030), tying insurance savings strictly to proprietary apps creates a walled garden. Consumers become tightly bound to manufacturer-backed insurance broking ecosystems, potentially reducing long-term market competition for renewals.
Conclusion
Hyundai’s UBI policy is a progressive step forward for connected mobility in India, successfully modernizing the insurance renewal process. However, its future success relies on greater algorithmic transparency (explaining how scores are weighed) and ensuring that infrastructure limitations (like heavy traffic idling) do not alienate urban drivers. The whole process can turn into a debate and court room drama as well as seen in mature market globally over the decades. Should You Avoid It? Unless you are absolutely sure about your driving, you should.

